
Fast Review · Bad Credit Considered · No Collateral

Emergency Business Funding
When Your Business Can't Wait

Quick Answer

A merchant cash advance (MCA) is typically the fastest form of emergency business funding. Review begins once your file, a signed application plus six consecutive months of business bank statements, is complete. For approved files, funding is commonly available within one business day, though the funding provider sets the actual timeline and it is never guaranteed. 500 FICO minimum, no collateral required, and a prior bank decline does not automatically rule you out.

2-4 hrs
Typical decision time
Often same day
Funding once approved
500 FICO
Minimum credit score
$10K-$1M
Advance amounts
Apply Now (5 Minutes) Call 330-238-3003

When You Need Business Capital Fast

Businesses don't run on 30-day loan timelines. Equipment breaks. Tax payments come due. Payroll can't wait. A key supplier demands immediate payment. When a cash flow crisis hits, you need a solution measured in hours, not weeks.

A merchant cash advance (MCA) was designed for exactly this. No collateral. No tax return requirement. No lengthy application process. On a complete file, the provider returns a decision after review, and funding follows once approved. The funding provider sets the actual timeline, and it is never guaranteed.
🔧
Equipment emergency
Oven breaks, a truck needs repair, HVAC fails. Emergency capital can get the fix underway fast, before the outage costs you more in lost revenue than the repair itself.
💵
Payroll gap
Payroll is due and deposits are short. Emergency funding, once approved, can help you make payroll and stay compliant without missing a pay date.
📋
Tax payment due
An IRS or state tax deadline is close. Emergency capital can help you make the payment before penalties and interest start accruing.
📦
Supplier demand
A key supplier is threatening to cut you to cash-on-delivery terms. Capital to settle the balance can help you keep normal terms and protect your supply chain.
🏠
Lease renewal
A landlord requires a deposit to renew. Emergency funding can cover it so you don't risk losing the location over a timing gap.
📈
Unexpected slow month
One bad month and fixed costs pile up fast. Emergency capital can bridge a genuine short-term gap. It is not meant to cover an ongoing loss; see the guidance below on when it isn't the right tool.
🛡️
Compliance deadline
A lapsed insurance policy or business license can threaten your ability to operate. Emergency capital can help you cure the lapse before it becomes a shutdown.
⏱️
Time-limited opportunity
A supplier discount, inventory lot, or lease opportunity with a short decision window. Emergency funding can move fast enough to act, when the underlying opportunity is genuinely real.
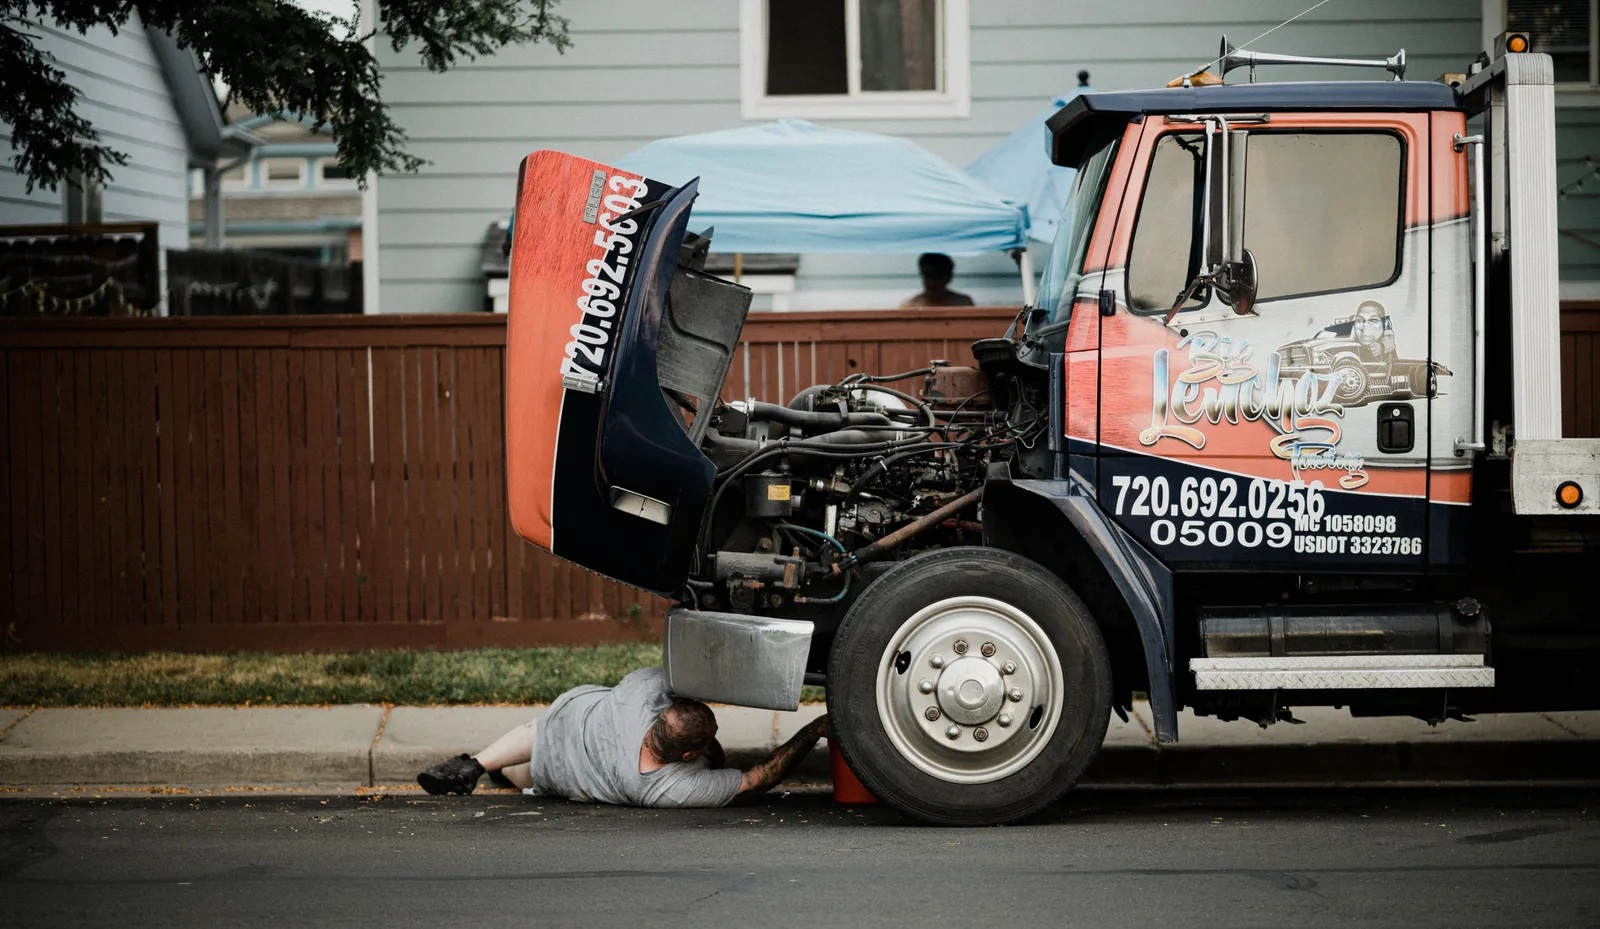
Mechanic lying under a box truck parked at the kerb, working on it.
A vehicle out of service is the version of an emergency most owners actually meet: the work is booked and the truck will not start.

When Emergency Funding Is (and Isn't) the Right Move

Emergency funding is a bridge for a specific, real, time-boxed gap. It is not a fix for a business that is structurally losing money every month. Before you apply, it's worth being honest with yourself about which situation you're actually in, because the two call for different solutions.

When emergency business funding fits vs. when to wait or compare options A two-column comparison. Left column, emergency funding usually fits when: a single one-time event created the gap rather than an ongoing pattern; there is a clear near-term way to repay, such as incoming revenue or a finished job; or waiting on a slower option would cost more than the emergency capital itself. Right column, wait or compare options first when: deposits have declined for several months with no clear turnaround, pointing to a structural problem rather than a one-time emergency; there are more than a few business days before the deadline, making a bank line of credit or SBA option worth comparing; or the business is already carrying MCA payments that take a large share of deposits, so adding another would increase the pressure rather than relieve it. Emergency funding usually fits when: A single, one-time event created the gap, not an ongoing pattern in your deposits. You have a clear, near-term way to repay: incoming revenue, a finished job, or a return to your normal deposit pattern. A slower option would likely cost more than the capital itself, whether that's a lost contract, shutdown, or real penalty. Wait or compare options first when: A pattern of declining deposits over several months, not a single event, usually points to a structural problem, not a one-time emergency. You have more than a few business days before the deadline: a bank line of credit or SBA option may be worth comparing first. You're already carrying MCA payments that take a large share of deposits: adding another can add pressure, not relieve it.

If the cash gap keeps recurring month after month, emergency funding treats a symptom rather than the cause. Taking on more short-term capital when a business is structurally losing money increases what you owe without fixing what created the gap. In that situation, a hard look at the underlying numbers, pricing, staffing, or cost structure is usually worth more than another advance.

How Emergency MCA Funding Works

1
Apply online in about 5 minutes
Fill in your business name, industry, monthly revenue, and contact info. No lengthy application process.
2
Upload 6 consecutive months of business bank statements
All pages, non-redacted, straight from your business account. That's the documentation needed for review: no tax returns, no financial statements, no business plan. Personal statements are not accepted.
3
Receive a decision once your file is complete
The funding provider reviews your deposit history and revenue. Most complete files receive a decision within a few hours, though timing depends on the provider and is not guaranteed.
4
Review and accept your offer
Review the advance amount, factor rate, and holdback percentage. Sign electronically; no in-person visit is required. Actual pricing and terms are set by the funding provider after review.
5
Funding hits your account
Files approved and signed earlier in the day reach the provider’s funding queue sooner. Others are commonly funded by the next business morning. The exact timing is set by the funding provider and is not guaranteed.

Every step above can move fast, but only the review stage is set by the funding provider, and only for a complete file. Here's the shape of it:
Emergency business funding timeline, from a complete file to funds sent Four-step flow: File Submitted, a signed application plus six months of business bank statements, then Provider Reviews the deposit history, balance, and revenue, then Decision Returned, then Signed and Funded once approved. A note below explains that missing statements or an incomplete file is the most common cause of delay, and that timing is set by the funding provider, not T.A.G., and is never guaranteed. File Submitted Application + 6 months of business bank statements → Provider Reviews Deposits, balance, revenue history → Decision Returned Often within hours for a complete file → Signed & Funded Same day or next business morning Missing statements or an incomplete file is the most common cause of delay. Review and funding timing are set by the funding provider, not T.A.G., and neither is guaranteed. A complete file moves you faster than urgency alone.
Gloved hands tightening a fitting on pipework with a wrench.
Plant and services failures rarely wait for a convenient month, which is why the repair usually gets paid for before the invoice or the insurance clears.

Emergency Funding Qualifications

These are the only hard requirements. If you meet them, you're eligible to apply:

✓ Time in business
6+ months operating
✓ Monthly revenue
$4,000+ in monthly deposits
✓ Credit score
500 FICO minimum
✓ US business
All 50 states + DC
Bank turndowns OK. Tax liens OK. Prior bankruptcy considered.

Review focuses on your deposit history, not on what a bank turned you down for. A prior decline elsewhere does not automatically rule out an emergency MCA review.

Ready to Apply? Start Here.

Short application. No hard credit pull to apply. Decisions often come back in hours for a complete file, though timing depends on the funding provider.

Apply Online Call 330-238-3003

Frequently Asked Questions

What is the fastest way to get emergency business funding?

A merchant cash advance (MCA) is typically the fastest form of emergency business funding. For a complete file, decisions often come back within a few hours, and funding is commonly available within 1 business day once approved. Requirements: 500 FICO minimum, roughly $4,000 or more per month in business revenue, and 6+ months in business. No tax returns, no business plan, no collateral: just 6 consecutive months of business bank statements and a short application. Timing depends on the funding provider and is never guaranteed.

Can I get emergency business funding with bad credit?

Yes. Merchant cash advances are approved mainly on monthly revenue deposits, not credit score alone. 500 FICO is the minimum. A bank turndown or a tax lien does not automatically disqualify you, and a discharged bankruptcy in your past usually does not either. If your business has $4,000 or more per month in verifiable deposits, you have a real chance of qualifying regardless of credit history. What typically does rule out an emergency application: an open, active bankruptcy case, an active IRS levy on your bank account, or fewer than 6 months in business.

How much emergency funding can I get?

Emergency MCA amounts generally range from $10,000 to $1,000,000, depending on your monthly deposits. Most businesses are considered for roughly 75% to 150% of their average monthly bank deposits. A business depositing $30,000 a month, for example, would typically be considered for $22,500 to $45,000 on a first advance, though the actual offer is set by the funding provider after review.

What documents do I need?

Two things: your six most recent consecutive, complete, non-redacted BUSINESS bank statements, and a completed application. No tax returns, no financial statements, no business plan. Personal bank statements are not accepted. A driver's license and a voided business check may be requested later, after approval, and should never be required to submit your file.

Can I get funded the same day?

It's a realistic outcome for a complete file, not a guarantee. Submitting your application with six months of business bank statements early in the day gets it to the provider sooner. If you're approved and sign in time, a wire can sometimes go out the same afternoon; ACH transfers typically take one to two additional business days to arrive. Files that miss the cutoff, or that need more documentation, commonly fund the next business morning instead. The funding provider sets the actual timeline.

What situations qualify as an emergency that MCA can help with?

Emergency MCA is commonly used for equipment repair or replacement, an unexpected tax payment, a payroll gap, a supplier payment needed to avoid a service cutoff, a lease renewal deposit, an inventory opportunity ahead of a peak season, or bridge capital after a genuinely unusual slow month. It is meant for a specific, one-time gap, not for a business that is losing money every month; see the guidance above on when to wait or compare other options first.

Related Resources

Same-Day Funding: What’s Realistic → Business Funding for Bad Credit → Funding After Bank Decline → MCA Qualification Guide → MCA for Payroll → MCA for Equipment →

Initial review uses a soft credit pull only. A hard credit pull typically occurs later, before final approval, and can affect your credit score by a few points.