

Georgia's economy is not just Atlanta. Metro Atlanta remains the state's largest concentration of corporate headquarters (Coca-Cola, Delta, Home Depot, UPS) and one of the country's busiest film and television production hubs: Georgia's film tax incentive drove roughly $2.6 billion in direct production spending in fiscal year 2024 alone. But beyond metro Atlanta, Georgia runs on several distinct regional economies: the Port of Savannah's container and logistics corridor, Augusta's cyber and health-system employment base, Columbus's finance and defense-contracting mix, and the farm and food-processing economy that runs through south and middle Georgia.
Georgia banking is conservative and concentrated heavily on commercial real estate lending, which leaves working-capital gaps for businesses without hard collateral to offer. MCA evaluates 6 consecutive months of business bank deposits and funds once the provider approves the file, which is why it serves Georgia's restaurant, construction, logistics, and agriculture-adjacent sectors regardless of which region of the state a business calls home.
A restaurant in Savannah, a healthcare practice in Augusta, and a manufacturer in Macon do not run on the same cash-flow calendar as an Atlanta film-support vendor. Revenue-based MCA underwriting looks at each business's own trailing bank deposits, so it fits each of these regions on its own terms instead of assuming one statewide pattern.
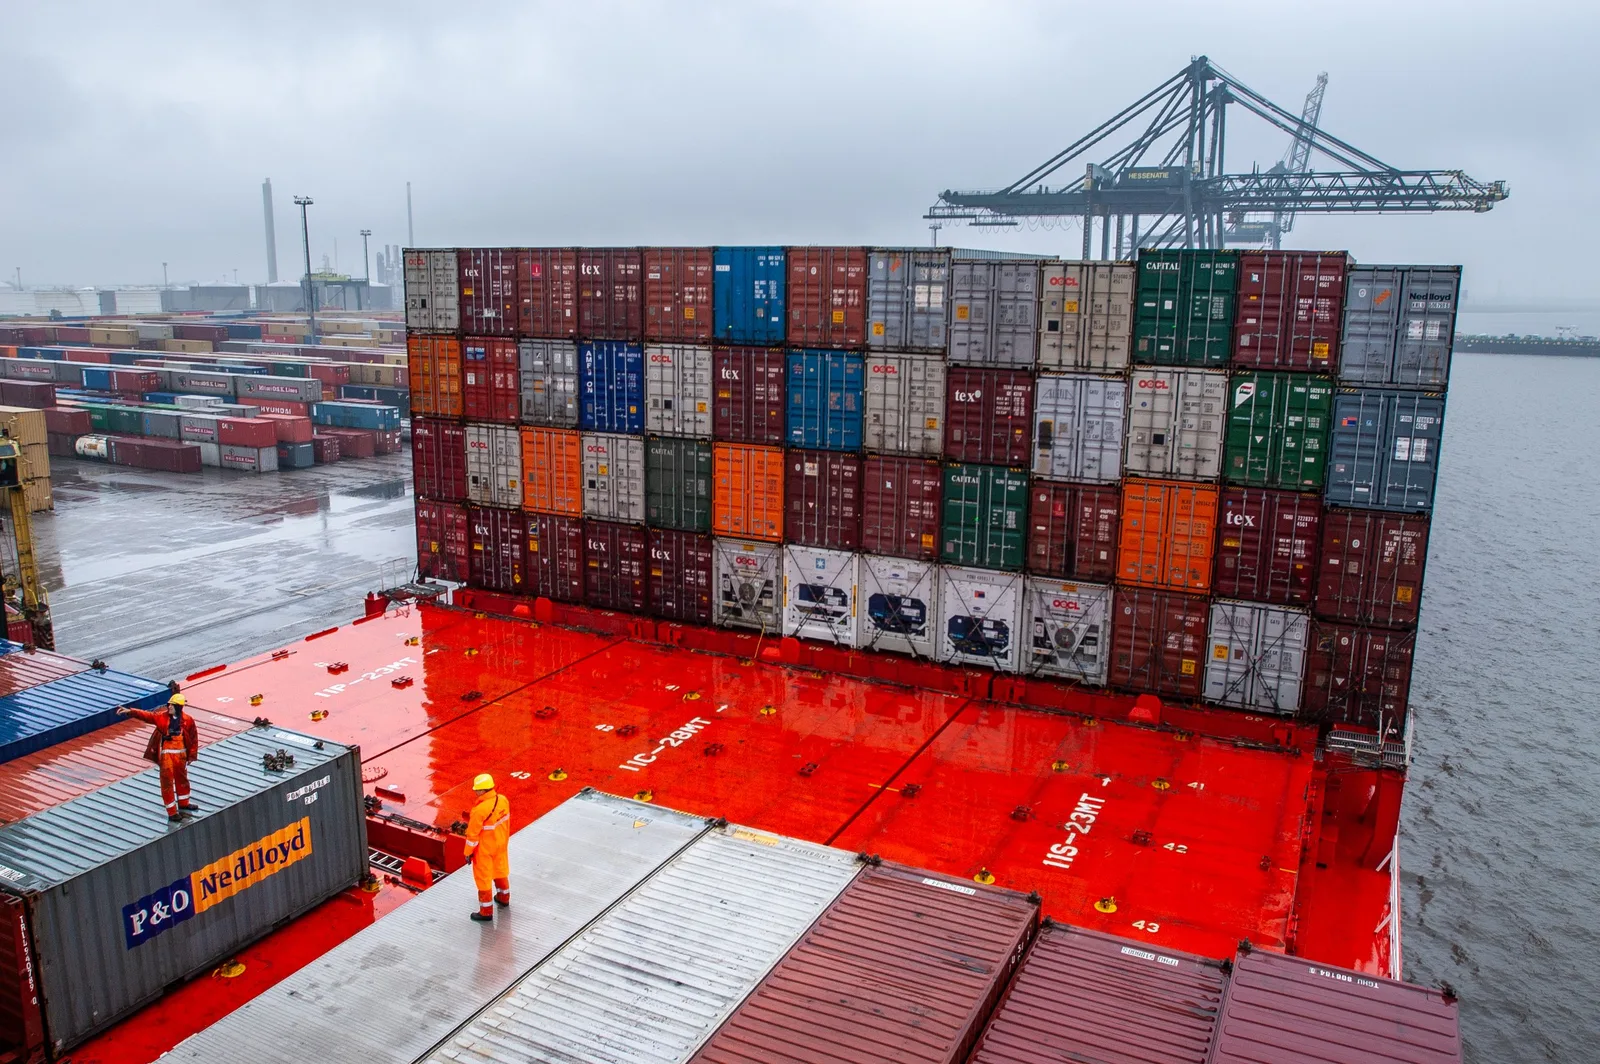
A container clearing Garden City Terminal, the largest single-terminal container facility in North America, does not pay the trucking company that delivered it. Drayage carriers and logistics vendors serving the Port of Savannah typically deliver a load, then wait out a customer's net-30 or net-60 invoice terms before payment actually lands. That gap between delivering freight and collecting on the invoice is a specific, time-boxed timing problem, not a sign the business is not working.
MCA bridges that specific gap using trailing bank deposits, not the invoice itself, as the basis for review. It is not the right tool for a logistics business that is not winning enough freight on its own; it is built for one waiting on payment terms for work it has already delivered.
Statements must be BUSINESS bank statements (personal statements are not accepted), 6 consecutive months, all pages, non-redacted. A driver's license and voided business check may be requested after approval; neither is required to start your file.
Served statewide: Savannah, Augusta, Columbus, Macon, Albany, Athens, Valdosta, Atlanta, and every one of Georgia's 159 counties.
Apply Online (10 min)
Basic business info + 6 consecutive months of business bank statements. Initial review uses a soft credit pull only.
Underwriting (1-3 hrs)
The funding provider reviews your deposits and revenue, not just FICO.
Offer and Approval
Advance amount, factor rate, and remittance structure. No hidden fees.
Funds Deposited
Wire to your GA business bank account. The funding provider sets the timing.
Catering, equipment rental, and logistics firms serving Georgia's film productions and seasonal agricultural harvests.
Pre-season purchasing for retail and restaurant businesses.
Materials and labor before contractor draw payments.
Bridging payroll during delayed payment cycles.
Commercial kitchen, salon, medical, or construction equipment.
New location deposits, build-out costs, market expansion.
| Factor | MCA via T.A.G. | Georgia Bank Loan |
|---|---|---|
| Decision time | 24-48 hours | 30-90 days |
| Minimum FICO | 500 | 680-720+ |
| Collateral | None required | Required (real estate, equipment) |
| Bank decline OK? | Yes | No |
| Tax liens OK? | Usually yes | No |
| Repayment | % of daily deposits (flexible) | Fixed monthly payment |
- MCA Advance Amount Formula
- Advance = Avg Monthly Deposits × 0.75 to 1.50
- Minimum to Qualify
- $4,000-$6,000/month in bank deposits, 6+ months in business, 500+ FICO
| Avg Monthly Deposits | Min Advance (0.75x) | Typical Advance (1.0x) | Max Advance (1.5x) |
|---|---|---|---|
| $15,000: rural Georgia farm supply or agribusiness | $11,250 | $15,000 | $22,500 |
| $18,000: Savannah café or retail shop | $13,500 | $18,000 | $27,000 |
| $35,000: Macon manufacturer | $26,250 | $35,000 | $52,500 |
| $40,000: Augusta healthcare practice | $30,000 | $40,000 | $60,000 |
| $50,000: Atlanta restaurant | $37,500 | $50,000 | $75,000 |
| $55,000: Columbus service or finance-support company | $41,250 | $55,000 | $82,500 |
| $70,000: Savannah drayage or logistics operator | $52,500 | $70,000 | $105,000 |
Georgia has one of the largest concentrations of Black-owned small businesses in the Southeast. Nationally, the Federal Reserve's 2024 Small Business Credit Survey found Black-owned businesses face financing denial rates around 39%, more than double the roughly 18% denial rate reported by white-owned businesses, and are more likely to be approved for less than they requested when they are approved. Revenue-based MCA underwriting, which looks at trailing bank deposits rather than the same credit-file signals a bank relies on, is one of the few funding paths not gated by that disparity.
Sources: U.S. Bureau of Economic Analysis, 2024 state GDP; U.S. Small Business Administration Office of Advocacy, 2024/2025 Georgia state profile; Federal Reserve 2024 Small Business Credit Survey.
Can a Georgia small business get a merchant cash advance?
Yes. Georgia businesses with 6+ months operating, $4,000-$6,000+/month in average deposits, and 500+ FICO can apply for MCA statewide: the Savannah port district, Augusta, Columbus, Macon, Atlanta, and Georgia's 159 counties overall.
What credit score do I need?
Minimum 500 FICO. The initial review uses a soft credit pull and looks primarily at your monthly bank deposits. A hard credit pull typically occurs later, before final approval, and can affect your credit score by a few points. Bank declines, tax liens, and prior bankruptcies do not automatically disqualify you.
How fast can a Georgia business get funded?
Review begins once your file is complete: a signed application plus 6 consecutive months of business bank statements. Most Georgia files get a decision once the provider reviews them, with funding following approval.
Does Georgia have disclosure requirements for MCAs?
Yes. Georgia enacted commercial finance disclosure requirements under SB 90, signed May 1, 2023 and effective January 1, 2024. The law requires providers of commercial financing transactions of $500,000 or less (loans, open-end credit, and accounts receivable purchases, including MCA) to disclose the total cost of capital, an APR-equivalent figure, and the repayment structure before the transaction is completed. T.A.G. provides full SB 90-compliant disclosures on every Georgia offer.
How much can a Georgia business qualify for with MCA?
Georgia businesses typically qualify for 75%-150% of average monthly bank deposits. An Atlanta restaurant averaging $50,000/month may qualify for $37,500-$75,000. An Augusta healthcare practice averaging $40,000/month may qualify for $30,000-$60,000. A Savannah drayage or logistics operator averaging $70,000/month may qualify for $52,500-$105,000. A rural Georgia agribusiness averaging $15,000/month may qualify for $11,250-$22,500. Advance amounts range from $5,000 to $2,000,000.
What Georgia industries qualify most easily for MCA?
Georgia's most active MCA markets include logistics and drayage serving the Port of Savannah, agriculture and food processing across south and middle Georgia, manufacturing from Macon to Columbus, healthcare statewide, construction, and restaurants and hospitality tied to Georgia's tourism and event calendar. Any Georgia business with $4,000-$6,000+/month in deposits qualifies regardless of industry or region.
Does T.A.G. specialize in minority-owned Georgia businesses?
Yes. T.A.G. Business Funding is a minority-owned ISO with a focus on serving underserved small business communities. Revenue-based underwriting looks at deposit history rather than the same credit-file signals a bank relies on, which is one reason it works for businesses traditional banks have historically declined.
Can a Georgia business with multiple locations get MCA across all of them?
Yes. Multi-location businesses (restaurant groups, retail chains, multi-site service companies) can apply for a consolidated advance based on combined deposit history across locations. T.A.G.'s network can structure advances up to $2,000,000 for established multi-location Georgia businesses with consistent revenue.
- SB 90: Georgia Commercial Finance Disclosure Law (APR-Equivalent Disclosure Required)
- Georgia enacted commercial finance disclosure requirements under SB 90, signed May 1, 2023 and effective January 1, 2024. The law applies to commercial financing transactions of $500,000 or less, including MCA. Providers must disclose the total cost of capital, an APR-equivalent figure, and the repayment structure before any agreement is signed. T.A.G. provides full SB 90-compliant disclosures on every Georgia offer.
Ready to Fund Your Georgia Business?
Apply in 10 minutes. Initial review uses a soft credit pull only. Review begins as soon as your file is complete.
Get My Offer MCA vs Business Loan