E-commerce sellers need capital to pre-buy inventory and scale ad spend before the resulting sales revenue arrives. Pennsylvania is a major East Coast economy spanning Philadelphia, Pittsburgh, and the Lehigh Valley fulfillment corridor.
E-commerce businesses in Pennsylvania qualify for MCA with 6+ months in business, $4,000-$6,000+/month in business bank deposits, and a 500+ FICO score. Initial submission is a signed application plus 6 consecutive months of business bank statements, nothing more. Decisions come back from the funding provider once your file is complete.
4-Point Qualification Breakdown
1
Revenue
$4,000-$6,000+/month in average business bank deposits
2
Bank Statements
6 consecutive months, $4,000+ average ending balance
3
Time in Business
6+ months of operating history
4
Business Ownership
Active Pennsylvania business bank account in the applicant's name
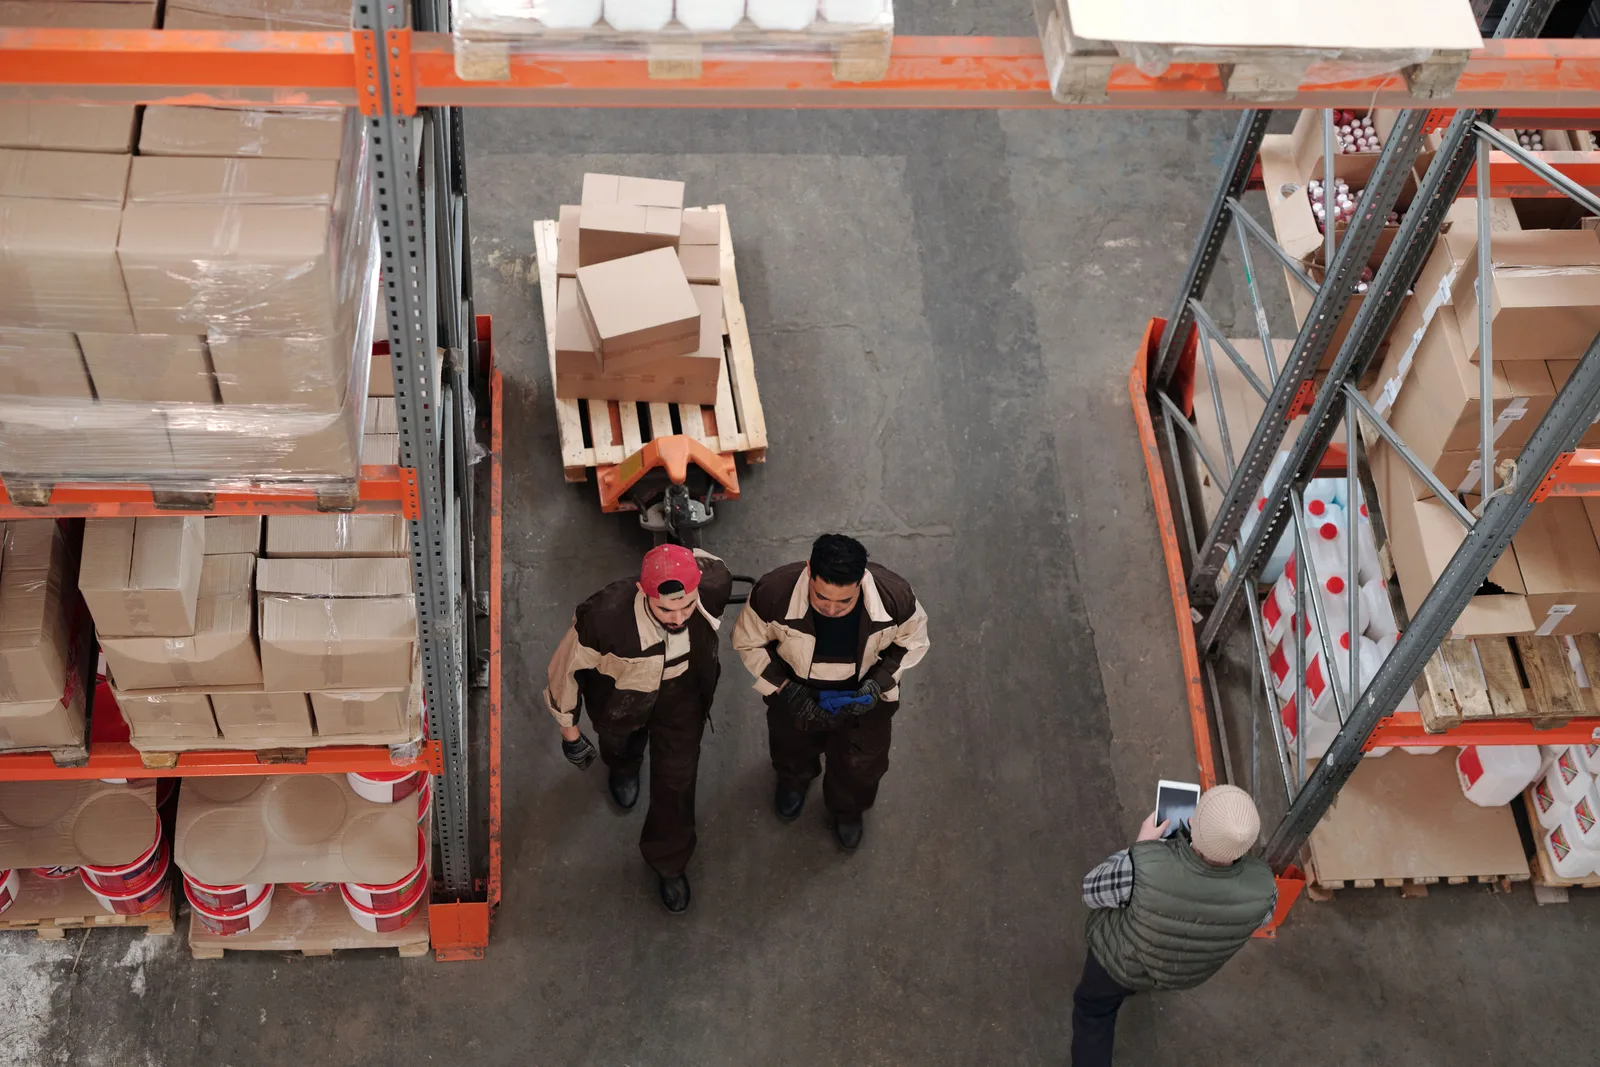
The Pennsylvania fulfillment corridor puts a lot of stock within a day of the East Coast.
How E-Commerce Businesses Use MCA Funding
Inventory pre-purchase ahead of peak-season demand
Paid advertising scaling on campaigns with a proven return
Fulfillment, warehousing, and 3PL costs at Pennsylvania distribution centers
New SKU launches and new marketplace expansion
Bridging the gap between a supplier deposit and port customs clearance on imported inventory
Pennsylvania's E-Commerce and Fulfillment Geography
Pennsylvania's e-commerce economy runs on geography as much as on any single factor. The Lehigh Valley, covering Allentown, Bethlehem, and Easton, sits where I-78 and I-81 cross, putting a fulfillment center there within a single day's truck run of New York City, Philadelphia, Washington D.C., and Baltimore. That access is a real reason national retailers and third-party logistics operators have built out warehouse and distribution space across the Lehigh Valley over the past decade, so a package leaving that corridor can reach a large share of the East Coast's population overnight.
Philadelphia adds a second advantage many sellers overlook: a working deep-water port. PhilaPort handles containerized import volume that clears directly at Pennsylvania docks rather than routing through a West Coast or New York/New Jersey port first, which matters for any seller who imports finished goods or private-label inventory instead of manufacturing domestically. For a Pennsylvania e-commerce business, this geography is a real operating advantage, but it creates a specific cash-timing pattern too: inventory has to be paid for, shipped, cleared, and received before it can be listed and sold, and the seller's bank account has to absorb that gap no matter how efficient the logistics are.
The Inventory Pre-Buy Cash-Timing Gap
The single most common reason a Pennsylvania e-commerce seller runs short on cash isn't a bad sales month; it's good timing working against them. A purchase order goes out to a supplier, usually with a deposit due on placement and the balance due before the goods ship. The container then spends weeks in transit and clearing customs, often through PhilaPort or a nearby East Coast port, before it ever reaches a Pennsylvania fulfillment center. Only after it's received, checked in, and listed does it start generating sales, and if that inventory was bought ahead of a peak season like Q4 holiday shopping, the sales revenue that pays for it doesn't show up until weeks or months after the money already left the business's account.
What a Factor Rate Actually Costs (Not a Loan)
A merchant cash advance is priced with a one-time factor rate, not an annualized interest rate. Example: a $20,000 advance at a 1.20 factor rate means $24,000 total repayment, a $4,000 cost of capital. That total is fixed at origination and repaid via a daily or weekly percentage of your bank deposits, not a fixed monthly loan payment.
Advance Amount
Factor Rate
Total Repayment
Cost of Capital
$20,000
1.20
$24,000
$4,000
Check Your Funding Estimate
Each carton leaving the door was bought before the revenue arrived.
When Pennsylvania E-Commerce MCA Fits, and When to Wait
MCA is built for a specific, real cash-timing gap, not as a general-purpose way to cover a business that isn't generating enough sales on its own. The comparison below is meant to help you decide before you apply, not after.
T.A.G. Business Funding
E-Commerce Funding in Pennsylvania: Review Starts Once Your File Is Complete
$4,000-$6,000+/month revenue, 6 consecutive months of statements, 500+ FICO minimum.
500+ FICO minimum · 6+ months in business · $4,000-$6,000+/month revenue
FAQ
Can an e-commerce business in Pennsylvania get a merchant cash advance?
Yes. E-commerce businesses in Pennsylvania qualify for MCA with 6+ months in business, $4,000-$6,000+/month in business bank deposits, and a 500+ FICO score. Approval is based on your deposit history, not your credit score alone.
How many months of bank statements do I need?
Exactly 6 consecutive months of business bank statements, the same window used for the time-in-business minimum, with an average ending balance of $4,000+ across your 6 statements.
Is this a loan?
No. A merchant cash advance is a purchase of a fixed amount of your future receivables, not a loan. There is no interest rate, no fixed monthly payment, and no fixed maturity date. It is priced with a one-time factor rate applied to the advance amount.
How much could a Pennsylvania e-commerce business qualify for?
MCA amounts are typically 75%-150% of average monthly bank deposits. For example, a $20,000 advance at a 1.20 factor rate means $24,000 total repayment: a $4,000 cost of capital, repaid via a daily or weekly percentage of deposits rather than a fixed monthly bill.
Does Pennsylvania require MCA cost disclosure?
Pennsylvania does not currently have a commercial finance disclosure law equivalent to California's SB 1235. T.A.G. Business Funding voluntarily provides full cost disclosure, including the total payback amount and repayment structure, on every Pennsylvania offer before signing.
What documents do I need to apply, and are personal bank statements accepted?
A completed application and your six most recent, consecutive months of business bank statements, all pages and unredacted. Marketplace payout reports, Stripe or PayPal transaction summaries, and personal account statements are not a substitute for your actual business checking account statements. A driver's license and a voided business check may be requested later, after approval, but neither is required to start your application.
Does applying affect my credit score, and is a personal guarantee required?
Initial review uses a soft credit pull only, which does not affect your credit score. A hard credit pull typically occurs later, before final approval, and can lower your score by a few points, similar to any credit inquiry. Most MCA agreements, including offers arranged through T.A.G., also require a personal guarantee from the business owner.
Last reviewed: September 2026. T.A.G. Business Funding is an independent ISO partner, not a direct lender. All examples are illustrative. Advance amounts and rates vary by business profile and funder. Not financial advice.
Initial review uses a soft credit pull only. A hard credit pull typically occurs later, before final approval, and can affect your credit score by a few points.