Electrical Contractors Business Funding in New York
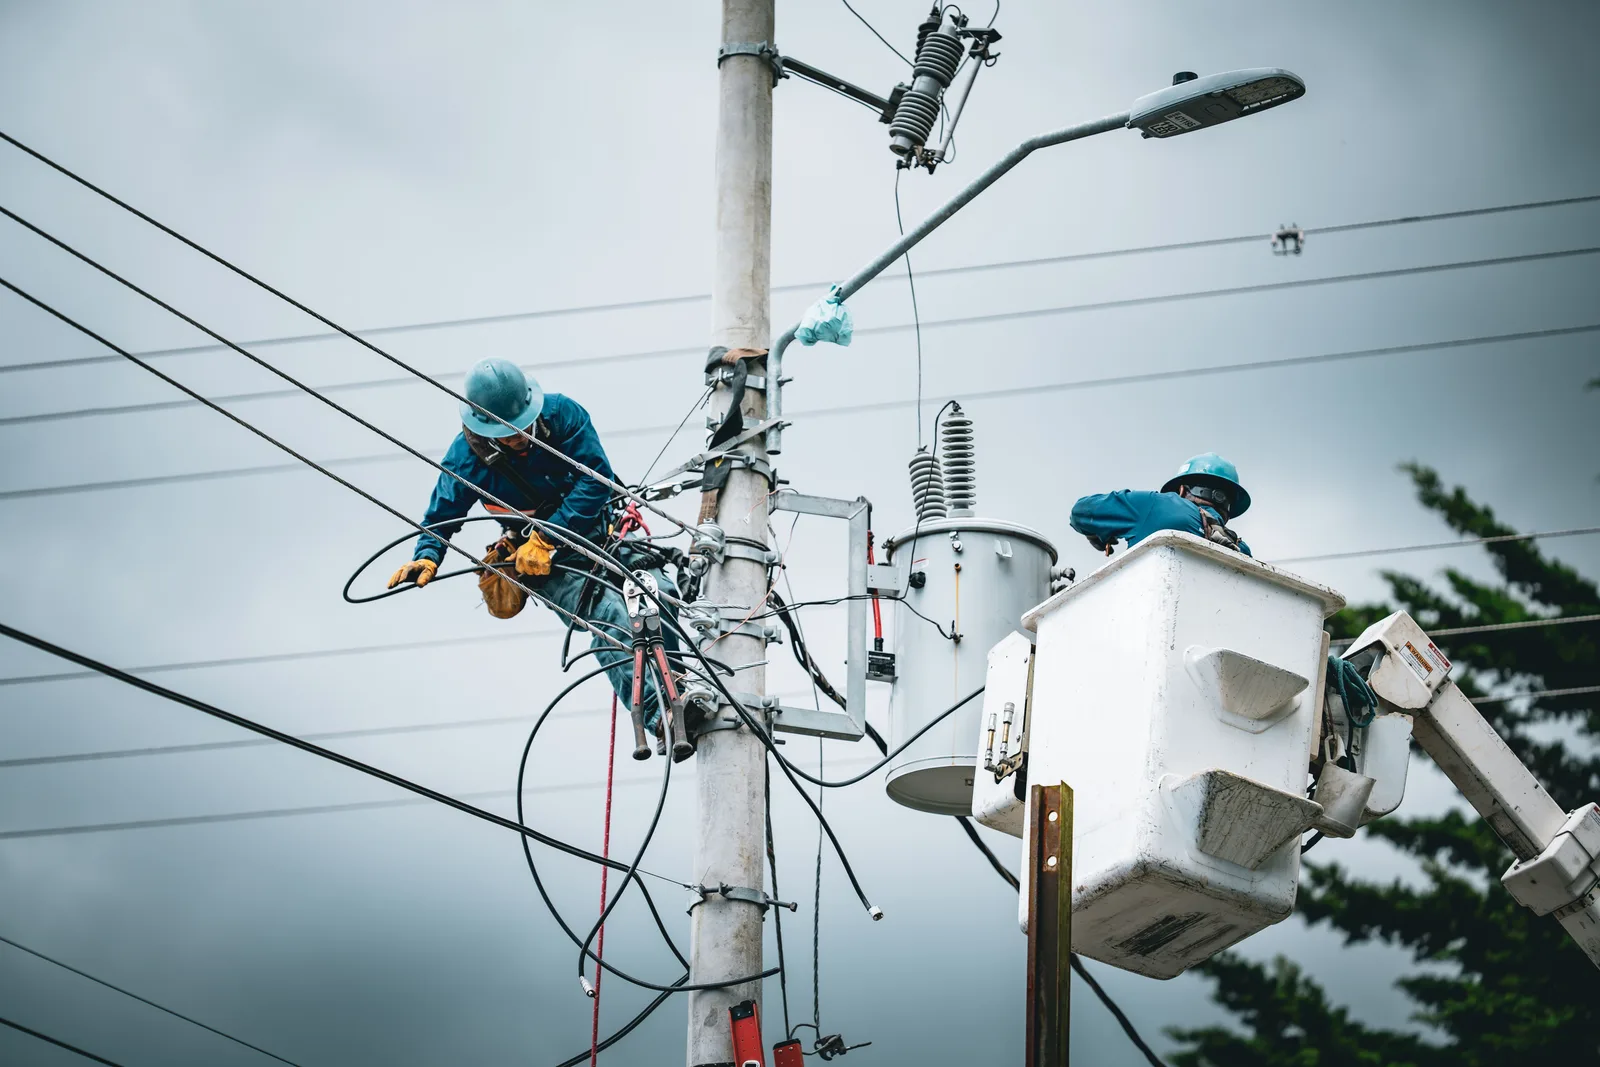
Electrical contractors need capital for bucket trucks, licensing, and apprentice payroll — bridging the gap between material costs and draw payments. New York is one of the largest state economies in the country, anchored by New York City.
Electrical Contractors businesses in New York qualify for MCA with 6+ months in business, $4,000 to $6,000+/month in business bank deposits, and a 500+ FICO. Initial submission is a signed application plus 6 consecutive months of business bank statements, nothing more. Timing is set by the funding provider after it reviews your file.
4-Point Qualification Breakdown
1
Revenue
$4,000 to $6,000+/month in average business bank deposits
2
Bank Statements
6 consecutive months, $4,000+ average ending balance
3
Time in Business
6+ months of operating history
4
Business Ownership
Active New York business bank account in the applicant's name
The city experience requirement concentrates licensed capacity, which makes qualified people expensive to hire and to keep.
How Electrical Contractors Businesses Use MCA Funding
Bucket truck or service vehicle
Tool and material inventory
Licensing and bonding
Apprentice and journeyman payroll
What actually limits growth for a New York electrical contractor
For an electrical contractor, the question that decides how fast you can grow is not the tax rate or the weather: it is how far one licence carries, and what you have to fund before a new market pays you anything.
Licensing in New York: local licensing only
New York has no statewide electrician licence. The dominant credential is the New York City Department of Buildings Master Electrician licence, which requires applicants to be at least 21 and to document roughly 7.5 years (about 10,500 hours) of satisfactory electrical experience within the prior ten years. Jurisdictions outside the city set their own requirements.
Portability: A New York City licence is a New York City licence — it does not automatically authorise work elsewhere in the state.
The experience requirement is among the steepest in the country, which is what makes qualified people expensive to hire and keep. Diagram built from this state’s own electrical licensing statute and board rules, cited on this page. Licensing requirements change; confirm current requirements with the issuing authority before relying on this summary.
What that means for your cash flow
The NYC experience requirement is among the steepest in the country, which concentrates licensed capacity and makes qualified people expensive to hire and retain. Combined with New York's operating costs and the deposit-and-progress-billing rhythm of city construction work, electrical contractors there routinely carry substantial payroll and material cost well ahead of collection.
A New York City licence is a New York City licence; it does not automatically authorise work elsewhere in the state. Licence structure as published by the issuing authority named on this page. Requirements change; confirm current rules with that authority before relying on this summary.
What a funder must disclose to you in New York
New York has enacted a commercial financing disclosure law (CFDL (Part 600 NYCRR)), so a funder providing commercial financing to a New York business must give you specified cost and term disclosures before you sign. Actual pricing, factor rate, payment structure, and term are determined by the funding provider after review.
Official New York sources
Verify licensing requirements against the authority itself rather than any third-party summary, including this one:
This is general information about New York licensing and financing, not legal advice. T.A.G. Business Funding is an independent funding intermediary, not a lender, not a licensing authority, and not a law firm. Licensing rules differ between jurisdictions within a state and change over time; confirm your own requirements with the authority above before making a business decision based on them.
Deposit and progress billing on city construction work leaves payroll and materials sitting well ahead of collection.
What a Factor Rate Actually Costs: Not a Loan
A merchant cash advance is priced with a one-time factor rate, not an annualized interest rate. Example: a $20,000 advance at a 1.20 factor rate means $24,000 total repayment, a $4,000 cost of capital. That total is fixed at origination and repaid via a daily or weekly percentage of your bank deposits, not a fixed monthly loan payment.
Advance Amount
Factor Rate
Total Repayment
Cost of Capital
$20,000
1.20
$24,000
$4,000
Check Your Funding Estimate
T.A.G. Business Funding
Electrical Contractors Funding in New York
$4,000 to $6,000+/month revenue, 6 consecutive months of statements, 500+ FICO minimum.
500+ FICO minimum · 6+ months in business · $4,000 to $6,000+/month revenue
FAQ
Can a electrical contractors business in New York get a merchant cash advance?
Yes. Electrical Contractors businesses in New York qualify for MCA with 6+ months in business, $4,000 to $6,000+/month in business bank deposits, and a 500+ FICO. Approval is based on your deposit history, not your credit score alone.
How many months of bank statements do I need?
Exactly 6 consecutive months of business bank statements, the same window used for the time-in-business minimum, with an average ending balance of $4,000+ across your 6 statements.
Is this a loan?
No. A merchant cash advance is a purchase of a fixed amount of your future receivables, not a loan: there is no interest rate, no fixed monthly payment, and no fixed maturity date. It is priced with a one-time factor rate applied to the advance amount.
How much could a New York electrical contractors business qualify for?
MCA amounts are typically 75%-150% of average monthly bank deposits. For example, a $20,000 advance at a 1.20 factor rate means $24,000 total repayment ($4,000 cost of capital), repaid via a daily or weekly percentage of deposits, not a fixed monthly bill.
Last reviewed: August 2026. T.A.G. Business Funding is an independent ISO partner, not a direct lender. All examples are illustrative. Advance amounts and rates vary by business profile and funder. Not financial advice.