Barbershop Business Funding

Barber Shop Funding
for Barbershops and Barbers

You built the clientele. Now you want new chairs, a renovated shop, or a second location. Banks want 2 years of P&L and collateral you don't have. Your regulars show up three times a month, and your deposit history is the proof. MCA looks at that deposit history and can move quickly once a provider approves your file, with no collateral required.

Quick Answer

Barbershops can get MCA funding to repair or replace equipment fast, based on 6 consecutive months of bank deposits. Initial review needs only a 1-page application plus those statements.
What Barbershops Use MCA For

Barber Chairs & Stations
Commercial barber chairs run $800-$3,000 each. A 6-chair shop requires $5,000-$18,000 in chair investment. Add mirrors, lighting, and station cabinetry for a full setup.
$5K-$25K typical
Shop Renovation
Flooring, ceiling, lighting, waiting area, mirrors, and retail display. A renovation transforms a dated shop into a destination barbershop. Full renovation runs $10,000-$40,000+.
$10K-$40K typical
Second Location
Build-out for a new shop location. Chairs, mirrors, flooring, plumbing, electrical, signage, and initial inventory. Barbershop build-out runs $20,000-$80,000 depending on size and market.
$20K-$70K typical
POS & Booking Software
Appointment management, online booking, payment processing, customer management, and retail POS. Full system setup runs $2,000-$8,000 for hardware and first-year software.
$3K-$10K typical
Branding & Signage
Exterior signage, interior branding, merchandise (branded apparel, products), website, and local advertising. A full brand refresh drives foot traffic and premium pricing.
$5K-$15K typical
Shampoo & Treatment Area
Adding a shampoo station, wash bowls, and scalp treatment area expands service menu and average ticket. Installation runs $5,000-$15,000 including plumbing and equipment.
$5K-$15K typical
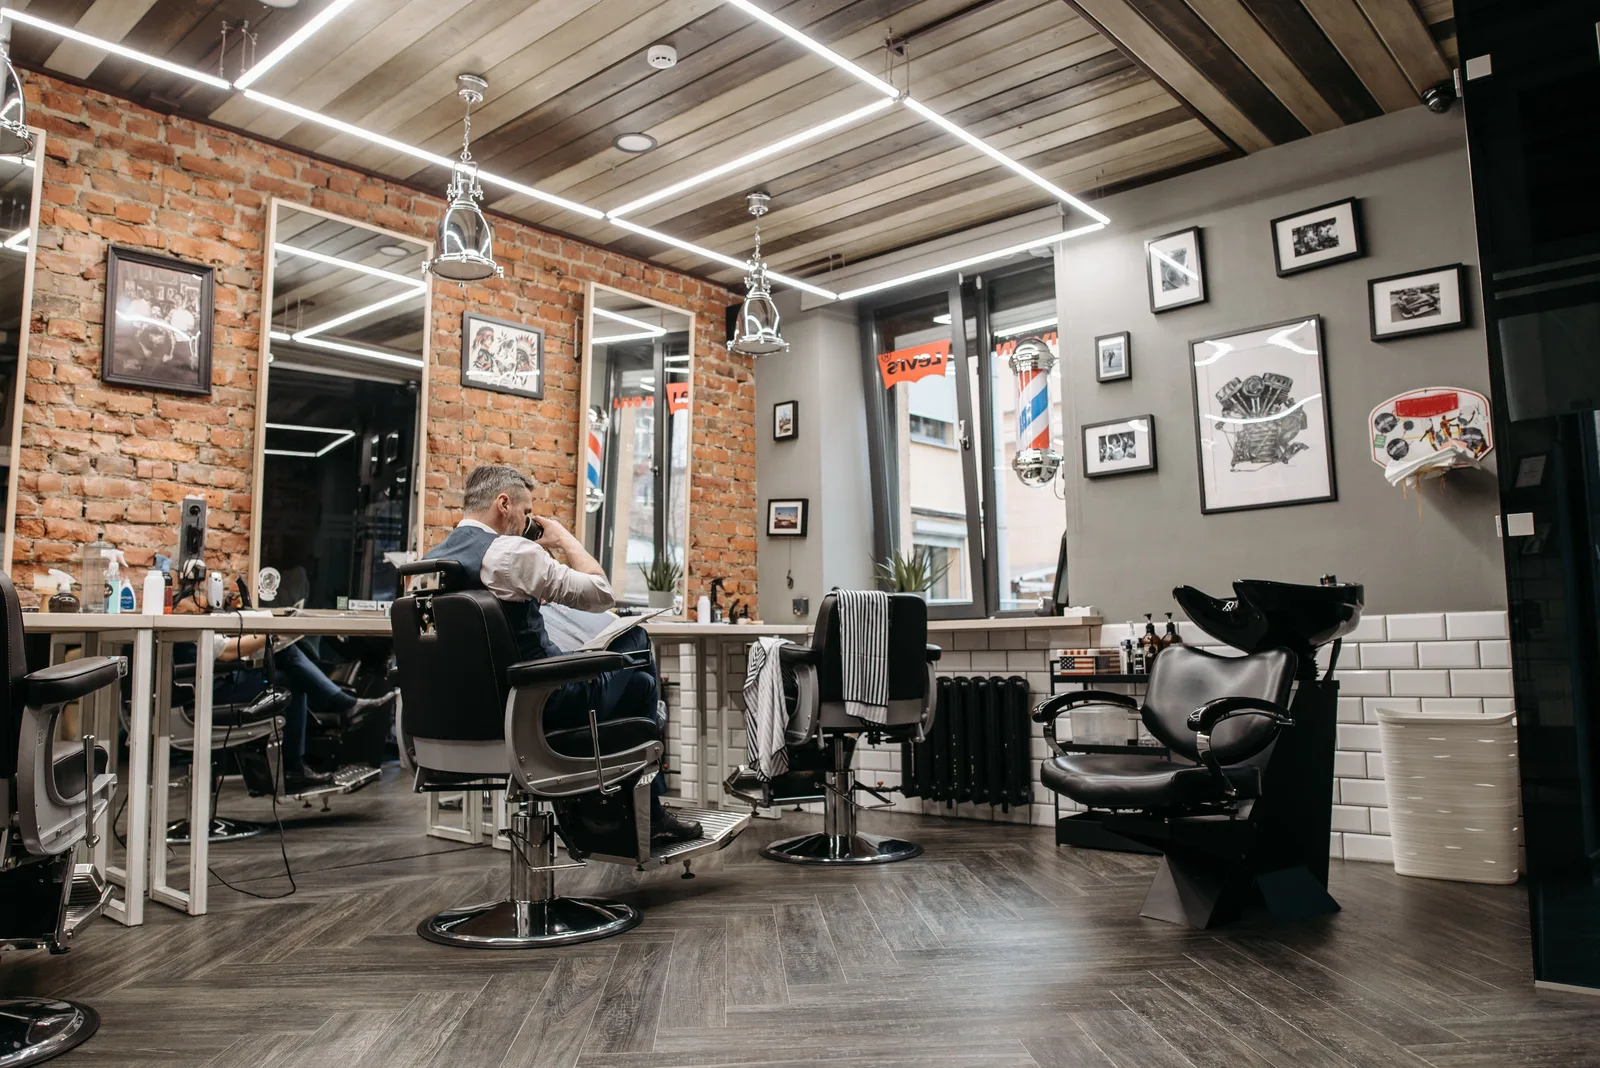
Barbershop floor with several styling chairs and wall mirrors, one barber working on a client at the far station
An empty station earns nothing. The arithmetic below is about what one more working chair adds to a week.

Why One New Chair Pays for Itself Fast

A single working chair generates monthly revenue well past its own cost, which is why chair purchases are one of the fastest-paying-back uses of barbershop capital.

One barber chair's monthly revenue compared to its one-time purchase cost A comparison of two bars. The chair cost bar is short, roughly 800 to 3000 dollars as a one-time purchase. The monthly revenue bar from that same chair at 8 clients a day, a 40 dollar average ticket, and 25 business days a month is roughly 8000 dollars, several times larger, shown as a much taller bar. Chair cost $800-$3,000 one time Revenue from that chair ~$8,000/month at 8 clients/day, $40 ticket

This is a simplified illustration, not a guarantee. Actual chair revenue depends on booking rate, ticket price, and how quickly a new barber fills the chair.

Barbershop MCA Approval Requirements

Monthly Deposits
Strong: $15,000+/month
Acceptable: $8,000-$15,000
Risk: Under $8,000
Personal FICO
Strong: 600+
Acceptable: 540-599
Minimum: 500
Time Operating
Strong: 2+ years
Acceptable: 6-24 months
Minimum: 6 months
NSF Frequency
Strong: 0 per month
Acceptable: 1-2 per month
Risk: 3+ per month

Barbershops that accept card payments generate consistent, automatic deposit records. Cash-heavy shops should ensure all revenue deposits to a business bank account for 90 days before applying.

What Underwriting Can Actually See

The same shop can look very different to a lender depending on where the money lands.

Card revenue creates a verifiable deposit trail; cash kept out of the bank does not Two columns. The left column, card and app payments, shows an unbroken line of deposit records reaching the business bank account, labeled visible to underwriting. The right column, cash kept out of the bank, shows a broken line that stops before reaching the account, labeled not visible to underwriting. Card & app payments Deposits reach the bank account Visible to underwriting Cash kept out of the bank Trail stops before the bank Not visible to underwriting

MCA underwriting reads bank deposit history, not point-of-sale totals. Revenue that never reaches the business account cannot count toward qualification, regardless of how real that revenue is.

Barbershop Funding: Illustrative Scenarios

Illustrative examples built from typical underwriting profiles for this industry, not records of specific named customers or guaranteed outcomes. Actual approval amount, timeline, and rate depend on your own bank statements and profile.
Full Renovation
8-year-old shop: complete interior overhaul
Owner wanted to update his 8-year-old shop: new flooring, 4 new barber chairs ($2,200 each), updated mirrors and lighting, new waiting area bench and TV setup. Total: $22,000. $18,000/month deposits, 565 FICO, 6 years. Bank said no to the unsecured renovation loan. The MCA request was approved quickly.
✓ Illustrative amount funded: $24,000
Second Location
First shop to second shop: new neighborhood location
Original shop doing $26K/month. Found a great corner retail space in a growing neighborhood. Build-out needed $55,000 (plumbing, 6 chairs, mirrors, flooring, signage). 580 FICO, 4 years. Bank required P&L from the new address, which was impossible before opening. MCA approved on existing shop's deposits.
✓ Illustrative amount funded: $58,000
Chairs & Equipment
Adding 2 chairs: expanding capacity for new barbers
Shop was turning away clients at peak hours. Added 2 more barber stations (chairs, mirrors, cabinets) to bring in 2 additional barbers. Cost: $9,500. $14,000/month deposits, 545 FICO, 3 years. Funded mid-month; both new stations were generating revenue within 3 weeks.
✓ Illustrative amount funded: $11,000
Branding & Marketing
Full rebrand: signage, merch, and local marketing push
Owner rebranded from a generic shop name to a distinct brand. New exterior signage, branded apparel line, website, and 3-month Google/Meta ad campaign. Total $14,000. $12,000/month deposits, 570 FICO, 4 years. Revenue up 22% in first 60 days post-rebrand.
✓ Illustrative amount funded: $15,000
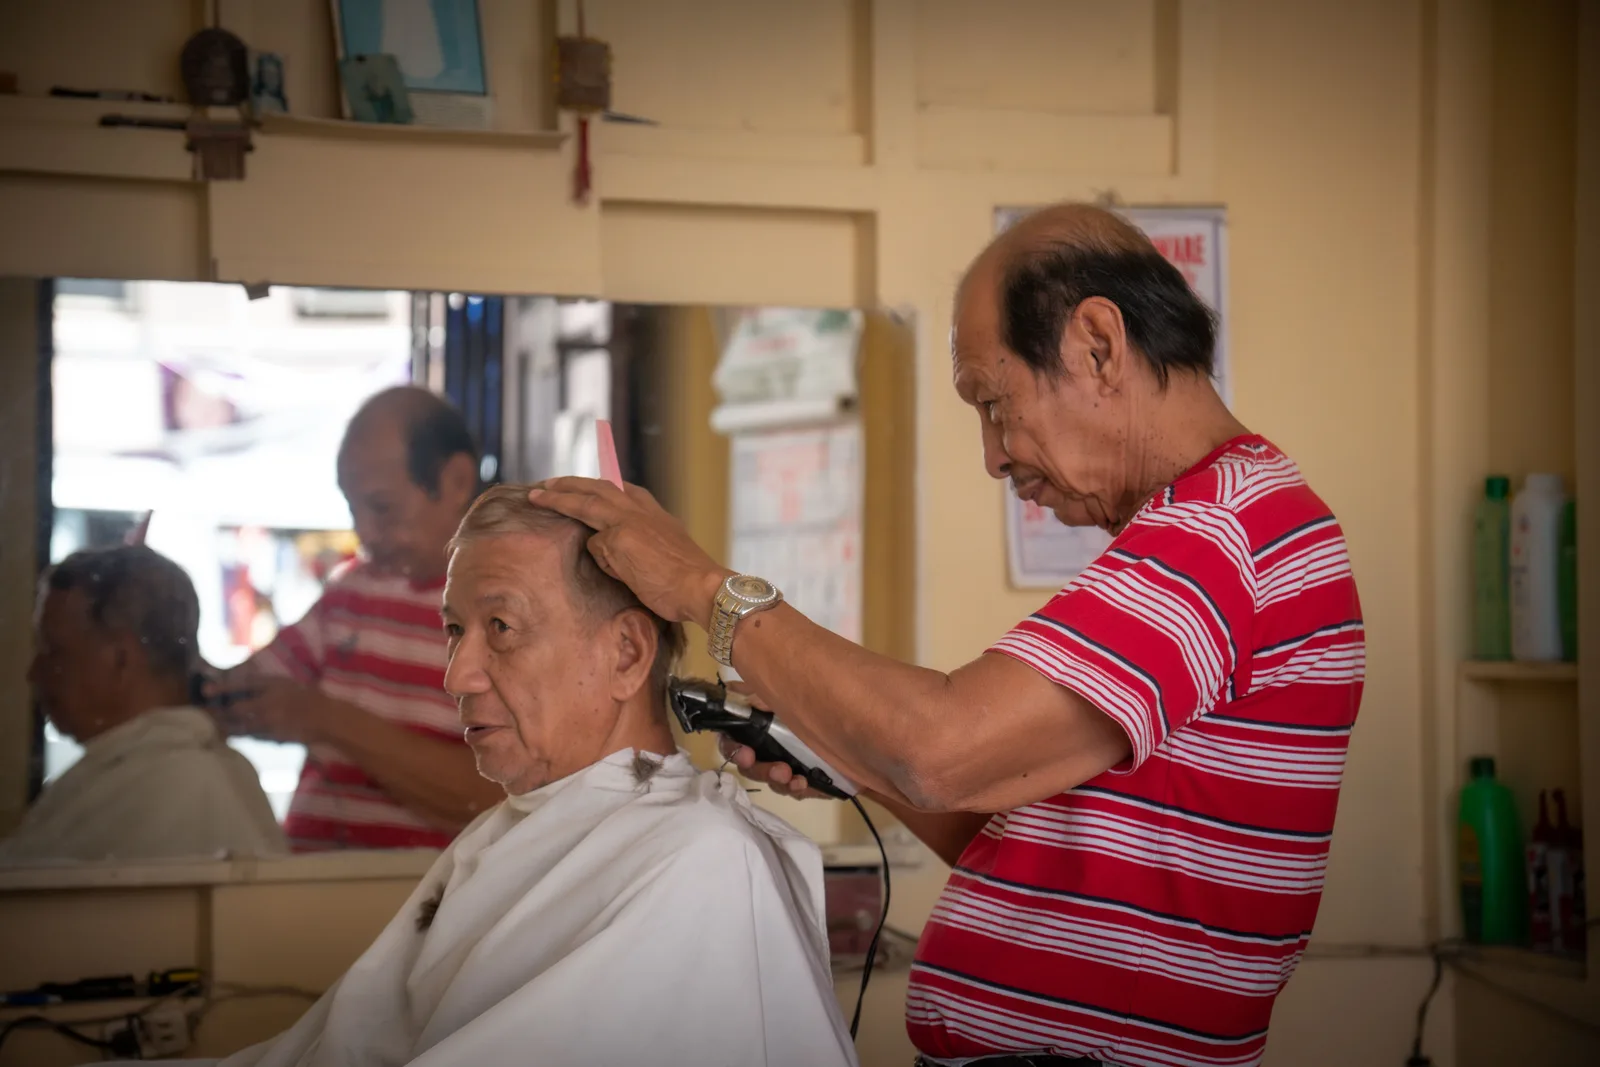
Barber using clippers on an older man’s hair while a second barber works behind him
Card and cash takings from days like this are the deposit history a provider actually reviews.

How Much Can Your Barbershop Qualify For?

MCA amounts are typically 75%-150% of average monthly bank deposits. Use this formula to estimate your range before applying.

Barbershop MCA Estimate Formula

Monthly Deposits = Chairs × Clients per Chair per Day × Avg Ticket × Business Days

Example: 6-chair shop / 8 clients per chair daily / $40 avg cut / 25 business days = $48,000/month

→ At $48,000/month: qualifies for $36,000-$72,000 MCA (75%-150% of monthly deposits)

Barbershop funding options compared: credit requirements, collateral, and amounts
Funding Type MCA via T.A.G. Bank Term Loan SBA Loan Equipment Lease
Decision timeFast, set by provider2-4 weeks30-90 days3-7 days
Min. FICO500660+640+600+
Collateral requiredNoneEquipment or real estateOften personal assetsEquipment being leased
Bank decline OK?YesNoLikely noSometimes
Typical range$10K-$500K$25K-$500K$50K-$5MEquipment cost only

Barbershop Funding FAQs

Can a barbershop get funding to replace broken equipment?

Barbershops can get MCA funding to repair or replace equipment fast, based on 6 consecutive months of bank deposits. Initial review needs only a 1-page application plus those statements.

Can a barbershop get a merchant cash advance?

Yes. Barbershops qualify with 6+ months operating, $4,000-$6,000+/month in deposits, and 500+ FICO. MCA funds once the provider approves your file with no equipment collateral and no barber license required in underwriting.

Can an independent barber (booth renter) get MCA?

Booth renters need a legal business entity and a dedicated business bank account with $4,000-$6,000+/month in deposits. Booth renters who process cards consistently build the deposit history needed to qualify. Cash-only booth renters face a documentation challenge without consistent bank deposit records.

Can a barbershop with cash-heavy revenue get MCA?

MCA qualification requires verifiable bank deposit history. Cash-heavy shops should accept cards (Square, Clover, etc.) and deposit all cash consistently to a business account. 6 consecutive months of consistent deposits is the qualifying window. Start building that history now if you're not already depositing consistently.

Can a barbershop owner use MCA for a second location?

Yes. Second location build-out is a common barbershop MCA use. Barbershop build-outs run $20,000-$80,000 depending on size. MCA qualifies based on the existing location's deposit history. The new location's lack of revenue history is not a disqualifier.

What do barbershops use MCA for most often?

Most common: shop renovation, barber chairs and stations, second location build-out, POS and booking systems, and branding/signage. Renovation and second location are the top two by dollar volume. Chair and equipment purchases are most frequent by transaction count.

Does a barbershop need a barber license to qualify for MCA?

No. MCA underwriting does not require state barber licensing. Qualification is based on business bank deposit history, time in business, and personal FICO only.

How much can a barbershop qualify for with an MCA?

Barbershop MCA amounts are typically 75%-150% of average monthly bank deposits. A 6-chair shop averaging $35,000/month in deposits can qualify for $26,000-$52,000. Shops with consistent card processing, longer operating history, and 580+ FICO typically qualify at the upper end of the range. Apply to see your actual offer based on your 6-month bank statement average.

What credit score does a barbershop owner need for MCA?

The minimum FICO score is 500. Most approvals come from shops with 540+ FICO and consistent monthly deposits with few NSFs. A 580+ FICO combined with $15,000+/month in deposits and clean bank statements typically produces the most competitive factor rate offers.

Barbershop Owner? Get Funded once the provider approves your file.

One-page application, 6 consecutive months of bank statements. No collateral, no barber license required. Renovation, chairs, and second location are all fundable uses.

Or call/text: 330-238-3003

New to Merchant Cash Advances?

What Is an MCA? A Complete Guide Pros & Cons Qualification Guide Cost Calculator MCA Rates 2026

T.A.G. Business Funding

See If Your Business Qualifies

500 FICO minimum. Bank declines OK. Revenue matters more than credit score. Funding timing is set by the funding provider after review.

Apply Now → Call 330-238-3003
✓ No obligation ✓ Soft pull to start ✓ Free to apply ✓ Bank declines welcome

500 FICO minimum  ·  $4K-$6K+/month revenue  ·  Funding timing is set by the funding provider after review
